Investing Education · Every Dollar Grows
401(k) Rollover Options: What to Do With an Old 401(k)
Compare leaving your old 401(k) in place, moving it to a new employer plan, rolling it to an IRA, or taking a distribution—without creating avoidable taxes or giving up valuable plan features.
Quick Answer
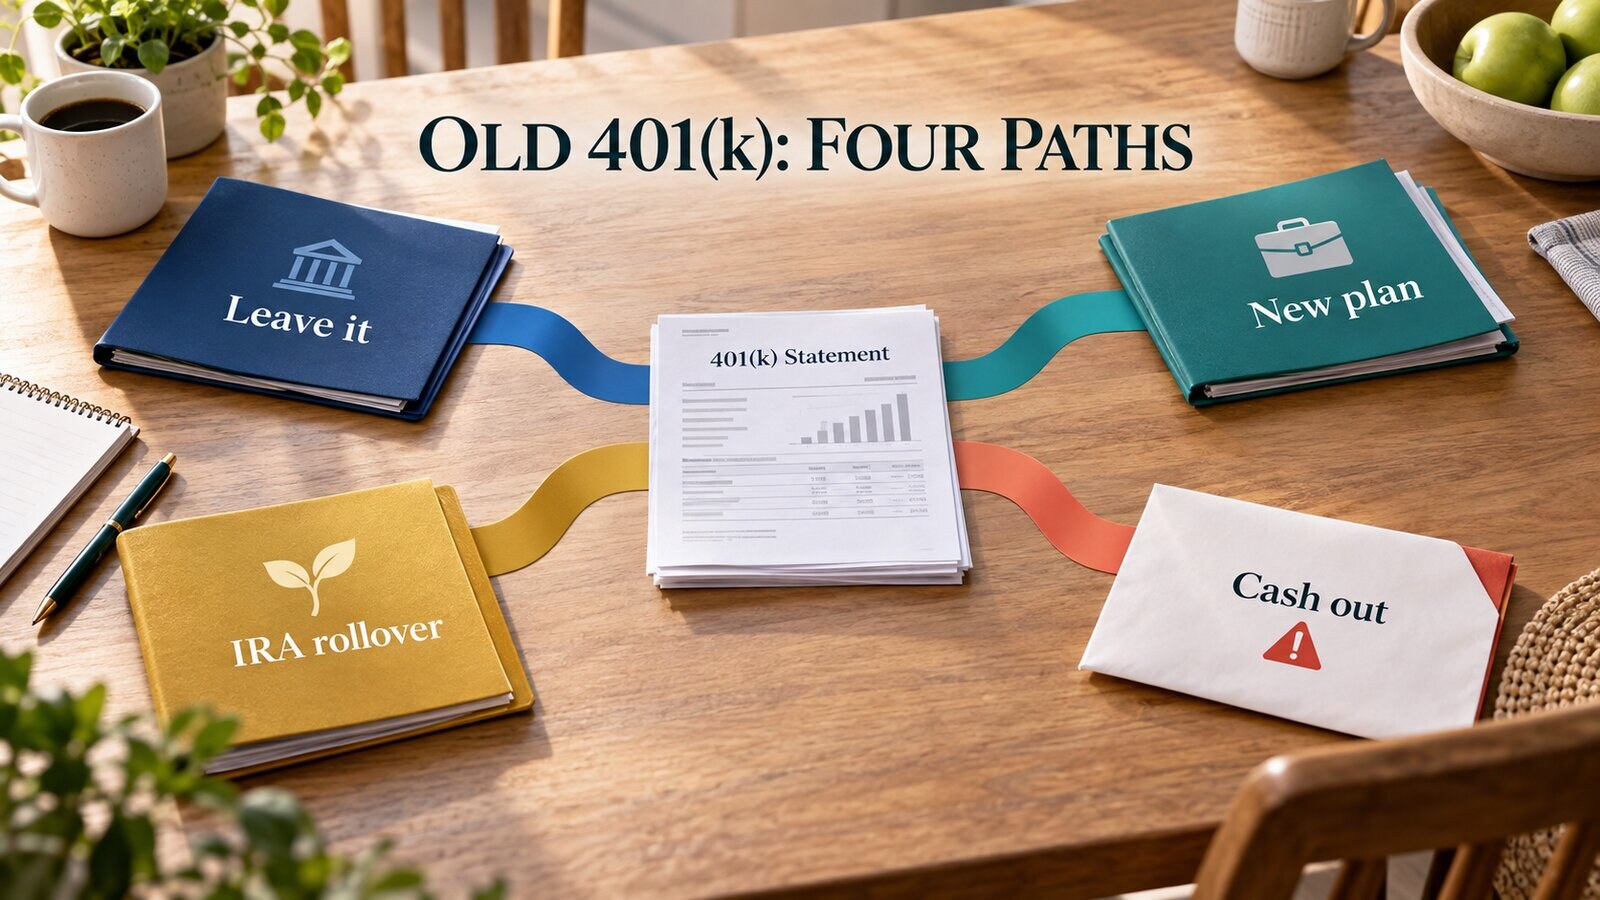
When you leave an employer, you generally have four major 401(k) rollover options: leave the money in the former employer's plan, roll it into a new employer's eligible retirement plan, roll it into an IRA, or take a distribution.
The best choice is not automatically the account with the most investment options. Compare fees, investments, withdrawal rules, creditor protection, the age-55 early-distribution exception, plan loans, Roth and pre-tax money, future Roth-conversion plans, and whether you hold employer stock before moving the account.
The Four Main 401(k) Rollover Options
1. Leave It in the Old 401(k)
Keep the existing plan if the employer allows it.
This may preserve low-cost institutional funds, ERISA plan protections, and certain withdrawal features.
2. Roll It Into a New Employer Plan
Consolidate the old balance into a new 401(k), 403(b), or other eligible employer plan if that plan accepts rollovers.
This can simplify management while keeping the assets inside an employer-sponsored retirement-plan structure.
3. Roll It Into an IRA
Move the account to a traditional rollover IRA, with Roth dollars generally directed to an appropriate Roth account.
IRAs can provide broader investment choice, but different withdrawal, creditor, fee, and tax-planning rules may apply.
4. Take a Distribution
Withdraw some or all of the account instead of keeping it inside retirement accounts.
Taxable amounts generally become current income, and an additional 10% federal early-distribution tax may apply if no exception is available.
Option 1: Leave the Money in the Former Employer's 401(k)
Doing nothing can be a legitimate retirement decision.
A former employer's plan may offer:
- low-cost institutional investment options,
- a strong target-date fund lineup,
- ERISA protections,
- access to the age-55 separation exception when applicable,
- stable-value or other plan-specific investments,
- and simple access to familiar holdings.
Possible disadvantages include maintaining another account, limited investment choices, higher plan expenses, weaker service after leaving the employer, or restrictions on partial withdrawals.
Small balances may not be allowed to stay forever
Current federal rules allow qualified plans to include mandatory-distribution provisions for certain vested balances of up to $7,000.
The exact treatment depends on the plan. For mandatory distributions above $1,000, federal rules generally require an automatic rollover to an IRA if the participant does not make another election.
Check the former plan's summary plan description instead of assuming the account can remain indefinitely.
Option 2: Roll the Old 401(k) Into Your New Employer Plan
If the new employer's plan accepts incoming rollovers, combining accounts can simplify retirement management.
Potential advantages include:
- fewer accounts to manage,
- continued employer-plan protections,
- keeping pre-tax retirement assets out of traditional IRAs,
- access to the new plan's institutional investment menu,
- and potentially simpler portfolio rebalancing.
But consolidation is helpful only if the receiving plan is good.
Compare:
- fund expenses,
- plan administrative fees,
- investment options,
- withdrawal flexibility,
- loan rules,
- and service quality.
A new plan is not required to accept every rollover. Confirm eligibility with the receiving plan before initiating the transfer.
Option 3: Roll the 401(k) Into an IRA
A rollover IRA can provide broader investment choice than many employer retirement plans.
Depending on the custodian, an IRA may provide access to:
- ETFs,
- mutual funds,
- individual stocks,
- bonds,
- CDs,
- and other eligible investments.
More choice is not automatically better. An inexpensive institutional 401(k) can be more attractive than an IRA filled with expensive investments or advisory fees.
Before rolling to an IRA, compare:
- total account and investment expenses,
- available investments,
- advisory fees,
- withdrawal rules,
- creditor protection,
- Rule of 55 implications,
- and future Roth-conversion planning.
Option 4: Cash Out the Old 401(k)
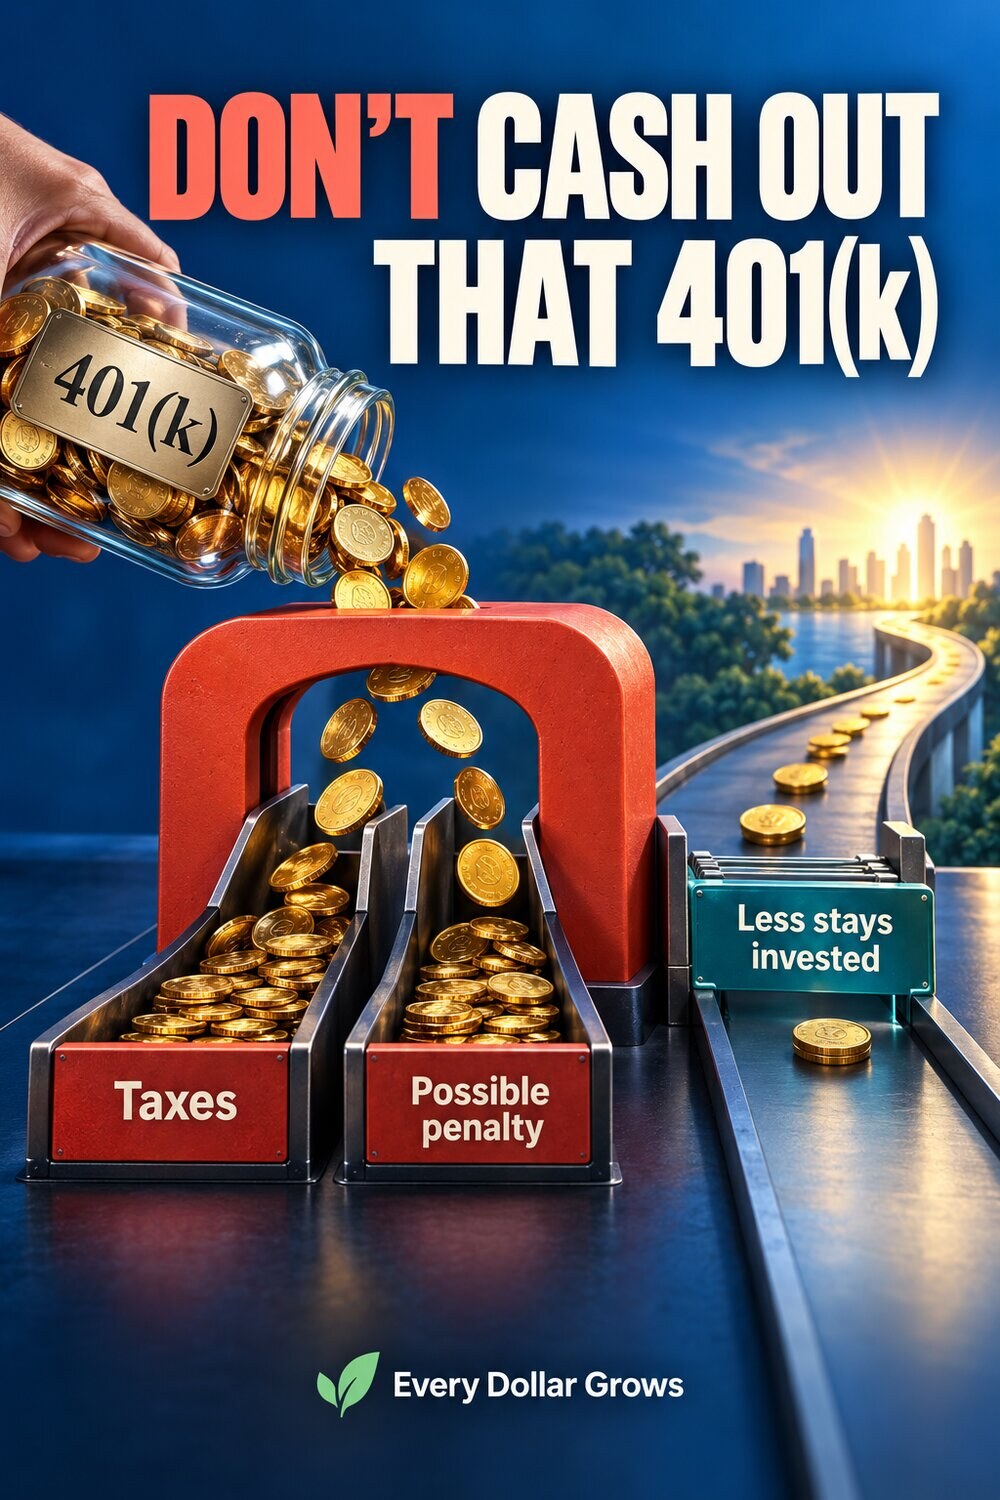
Taking the money out permanently can be the most expensive option because it can combine current income tax, possible additional early-distribution tax, and the loss of future tax-deferred growth.
If pre-tax 401(k) money is distributed instead of rolled over, the taxable portion generally becomes ordinary income for that year.
If the participant is younger than 59½, an additional 10% federal early-distribution tax can also apply unless an exception is available.
A relatively small account balance can make cashing out feel harmless, but the long-term cost can be much larger than the current balance suggests.
Before cashing out, calculate:
- estimated federal income tax,
- state income tax where applicable,
- possible additional early-distribution tax,
- and the future growth the retirement money would no longer receive.
Direct 401(k) Rollover vs. a 60-Day Rollover
How the money moves can matter just as much as where it goes.
Direct rollover
With a direct rollover, the retirement plan sends the eligible distribution directly to the receiving retirement plan or IRA.
The check may sometimes be mailed to you, but if it is made payable to the receiving institution for your benefit, it can still qualify as a direct rollover.
Mandatory federal withholding generally does not apply to a direct rollover.
Distribution paid directly to you
If an eligible taxable 401(k) distribution is paid directly to you, the plan generally must withhold 20% for federal income tax.
You ordinarily have 60 days to complete an eligible rollover.
Why the 20% withholding matters
Suppose the eligible rollover distribution is $100,000. If it is paid to you, the plan generally withholds $20,000 and you receive $80,000. To roll over the entire $100,000, you would need to replace the withheld $20,000 with money from another source within the applicable rollover period. Otherwise, the portion not rolled over may become taxable and may also face an additional early-distribution tax.
For that reason, a direct rollover is often operationally simpler when the goal is to move the entire eligible balance.
The Rule of 55 Can Make the Old 401(k) More Valuable
This is one of the most important rollover issues for someone leaving a job in their 50s.
The federal 10% additional tax generally does not apply to distributions from a qualified employer retirement plan after separation from service if the separation occurs during or after the calendar year in which the participant reaches age 55.
The exception generally applies to qualified employer plans, not to IRAs.
That means someone age 55 through 59½ who may need access to an old 401(k) should evaluate this exception before automatically rolling the account into an IRA.
Pre-Tax and Roth 401(k) Money Need the Correct Destination
Not every dollar inside a 401(k) necessarily has the same tax treatment.
A plan may contain:
- pre-tax employee contributions,
- employer contributions,
- designated Roth 401(k) contributions,
- and sometimes after-tax employee contributions.
Pre-tax 401(k) money can generally move to a traditional IRA or eligible pre-tax employer plan without creating current taxable income.
Moving pre-tax retirement money to a Roth IRA, however, is generally a taxable Roth conversion.
Designated Roth 401(k) money can generally be rolled to an eligible Roth destination.
If the account contains several tax sources, ask the plan administrator to identify each source before choosing rollover destinations.
Check Outstanding 401(k) Loans Before Leaving the Plan
A 401(k) loan can turn a straightforward rollover into a tax problem if it is ignored.
Some plans require an outstanding loan to be repaid after employment ends.
If the plan reduces the participant's account balance by the unpaid loan amount, a plan loan offset can occur.
A qualified plan-loan offset resulting from severance from employment or plan termination may receive an extended rollover period. Instead of the normal 60-day deadline, the participant may have until the federal income-tax return due date, including extensions, for the year in which the offset occurs.
The rules depend on the type of loan event. Get the plan's exact loan payoff and offset terms before initiating the rollover.
An IRA Rollover Can Affect Future Backdoor Roth Planning
Rolling pre-tax 401(k) money into a traditional IRA can have an unexpected effect on future Roth-conversion planning.
When someone has nondeductible basis in traditional IRAs and converts money to a Roth IRA, Form 8606 generally calculates the taxable and nontaxable portions using the combined value of the individual's traditional IRAs.
Traditional SEP and SIMPLE IRA balances can also be relevant to that calculation.
This is commonly called the pro-rata rule.
Someone who expects to use nondeductible traditional IRA contributions followed by Roth conversions should therefore evaluate whether moving a large pre-tax 401(k) balance into a traditional IRA would increase the taxable portion of future conversions.
Leaving the funds in an employer plan or rolling them into another eligible employer plan may produce a different result.
This is an area where tax advice can be particularly valuable.
Compare Fees, Investments, Services, and Protection
A rollover recommendation should not be evaluated only by comparing investment performance.
Compare the complete package.
| Factor | Questions to ask |
|---|---|
| Investment expenses | Are the old-plan institutional funds cheaper than comparable IRA or new-plan choices? |
| Administrative fees | What account, recordkeeping, advisory, or maintenance fees apply? |
| Investment menu | Does the account provide diversified investments that actually fit the plan? |
| Withdrawal access | Are partial withdrawals allowed? Does the Rule of 55 matter? |
| Creditor protection | What protections apply to the employer plan versus the IRA under federal and applicable state law? |
| Advice and services | What additional services are provided, what do they cost, and how is the adviser compensated? |
| Roth planning | Could a traditional IRA balance complicate future Roth-conversion planning? |
| Account simplicity | Is consolidation worth giving up any unique feature in the old plan? |
The U.S. Department of Labor specifically encourages investors to ask why a rollover recommendation is in their best interest and to compare expenses, investment options, services, and distribution choices.
Use the investment fee calculator to compare the long-term effect of recurring costs.
Employer Stock? Check Net Unrealized Appreciation Before Rolling
If the old 401(k) contains appreciated shares of the employer's stock, do not automatically roll everything into an IRA.
Certain lump-sum distributions of employer securities can qualify for special net unrealized appreciation, or NUA, tax treatment.
Under qualifying circumstances, appreciation that occurred while the stock was inside the plan may receive different tax treatment when the shares are eventually sold.
Rolling the employer shares into an IRA can eliminate the opportunity to use that specific treatment later.
NUA rules are specialized and can involve significant tax consequences. If employer stock represents a meaningful portion of the old 401(k), review the strategy with a qualified tax professional before completing the rollover.
A Real-World 401(k) Rollover Example
Assume a 57-year-old worker leaves an employer with $180,000 in the former employer's 401(k).
The worker's new employer has a 401(k), and an IRA provider is also offering a rollover account.
At first glance, moving everything into the IRA may seem attractive because the IRA offers far more investments.
But the worker expects to retire before age 59½ and may need access to some of the money.
Because the worker separated from that employer after reaching the applicable age, the age-55 exception may allow qualifying distributions from the old employer plan without the normal additional 10% early-distribution tax.
Rolling the entire account into an IRA could remove that particular exception.
The worker therefore compares:
- the old plan's withdrawal rules,
- its investment expenses,
- the new plan's investment menu,
- the IRA's costs and services,
- and expected retirement cash needs before age 59½.
The correct decision comes from those household constraints, not simply from which account offers the longest fund list.
401(k) Rollover Checklist
- Get the former plan's current fee and investment information.
- Check whether the old plan allows the balance to remain.
- Confirm whether the new employer plan accepts incoming rollovers.
- Separate pre-tax, Roth, and any after-tax sources.
- Check whether you have an outstanding plan loan.
- If you are between ages 55 and 59½, evaluate the separation-from-service exception before rolling to an IRA.
- If you hold employer stock, evaluate NUA before moving the shares.
- Consider whether a traditional IRA balance could affect future Roth conversions.
- Compare fund expenses, account fees, advisory costs, and services.
- Compare creditor-protection rules and withdrawal flexibility.
- Prefer a direct rollover when the goal is to move the full eligible balance without taking possession of the funds.
- Confirm the exact receiving account information before authorizing the transfer.
- Keep the rollover paperwork and Form 1099-R with your tax records.
Helpful Primary Sources
- IRS: Rollovers of Retirement Plan and IRA Distributions
- IRS Topic 413: Rollovers From Retirement Plans
- IRS: Exceptions to the Additional Tax on Early Distributions
- IRS: Retirement Plan Loan FAQs
- IRS: Form 8606 Instructions
- IRS Publication 575: Pension and Annuity Income
- U.S. Department of Labor: Questions to Ask About Rollover Advice
Frequently Asked Questions About 401(k) Rollover Options
Do I have to roll over my 401(k) when I leave a job?
Not necessarily. Many former employees can leave money in the old plan, although plan rules and small-balance mandatory-distribution provisions can affect that choice. Review the plan's rules before assuming the balance can remain indefinitely.
Is a 401(k) rollover taxable?
A properly completed rollover from pre-tax 401(k) assets to an eligible pre-tax retirement account generally does not create current taxable income. Moving pre-tax assets to a Roth account generally creates a taxable conversion.
Is it better to roll an old 401(k) into an IRA or a new 401(k)?
Neither destination is automatically better. Compare fees, investment choices, withdrawal rules, plan protections, future Roth-conversion planning, and account-management preferences.
What is the 60-day rollover rule?
If an eligible retirement-plan distribution is paid to you, you generally have 60 days from receipt to complete an eligible rollover. Employer-plan distributions paid directly to you generally face mandatory 20% federal withholding, so a direct rollover can avoid that withholding problem.
What is the Rule of 55?
The age-55 separation exception can allow qualifying distributions from an employer retirement plan without the normal additional 10% federal early-distribution tax when separation from service occurs during or after the year the participant reaches age 55. The exception generally does not apply to IRA distributions.
Can rolling my 401(k) to an IRA affect a backdoor Roth IRA?
It can. Form 8606 generally considers aggregate traditional IRA balances when determining the taxable portion of conversions involving nondeductible IRA basis. Adding pre-tax rollover assets to a traditional IRA can therefore change the tax calculation.
What happens to my 401(k) loan when I leave my employer?
The plan may require repayment or may offset the unpaid loan against the account. Certain qualified plan-loan offsets related to severance from employment can receive an extended rollover deadline through the applicable federal tax-return due date, including extensions.
Should I automatically roll employer stock into an IRA?
Not before checking whether net unrealized appreciation treatment could apply. Certain distributions of employer securities from a qualified plan can receive special tax treatment, and rolling the securities into an IRA can eliminate that opportunity.
Keep learning